Jesse Cohn · Elliott Investment Management
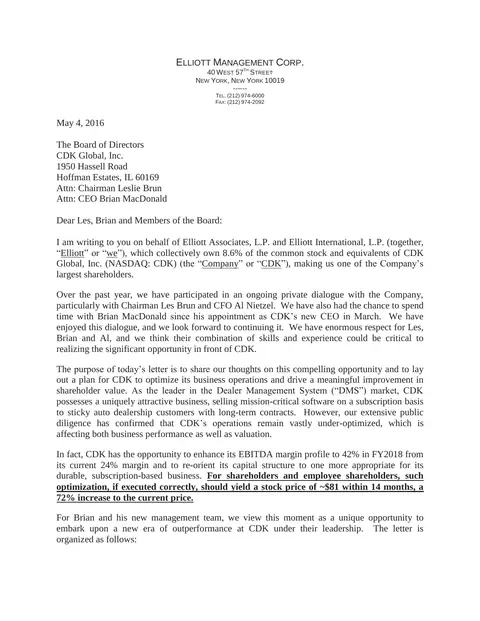
Elliott's May 2016 letter to the board of CDK Global
Published 4 May 2016Available at SEC.govActivist letter · Investment
The view as filed on 4 May 2016, not a statement of what the author thinks today.
What to notice
- 1
The benchmark is a direct rival: Elliott estimates that Reynolds & Reynolds runs its North America DMS business at about 55% EBITDA margins against 30% at CDK's comparable segment, with 8 facilities globally against CDK's 80.
Continue the investment thesis
See the 3 remaining takeaways on what this investor is arguing and why, and every analysis across the Letters & Theses library.
Checking what you can open…
“CDK is profoundly under-managed”
Why read it
It shows how an activist values a spin-off that was never run as a standalone company, using a direct competitor's margins and a leverage target to build a price target.
About this letter
Jesse Cohn, a senior portfolio manager at Elliott Management, wrote this letter on 4 May 2016 to the board of CDK Global, addressed to its chairman, Leslie Brun, and its chief executive, Brian MacDonald, who had been appointed in March. Elliott's two funds together owned 8.6% of CDK's common stock and equivalents, and the firm had been in a private dialogue with the company for the past year.
CDK, which leads the market for dealer management systems sold to car dealerships, had been spun off from ADP in October 2014. The letter is warm in tone towards the new leadership but blunt about the opportunity it believes has been missed. It describes Elliott's research, explains why the business is attractive, reviews the limited progress since the spin-off, and sets out a two-pronged Value-Maximizing Plan with a share price target.
Companies
- CDK Global, Inc. CDK
Themes
- margin expansion
- capital allocation
- breakup or separation
- cost discipline
- valuation
L3VLUP does not host this document. It belongs to Elliott Investment Management and is a public SEC filing; the notes above are L3VLUP’s reading of it.
More from Elliott Investment Management
The same argument, elsewhere
- Hayden Capital's Q2 2026 letter, on the "SaaS-pocalypse" and returns on reinvestment · Fred Liu, Hayden Capital
- Impactive Capital's "Wake Up WEX" letter to WEX shareholders · Impactive Capital
- Starboard Value's second letter to Autodesk shareholders, on returns and margin claims · Jeffrey Smith, Starboard Value
- Starboard Value's letter to Autodesk shareholders on margins and board change · Jeffrey Smith, Starboard Value
Holdings named in this letter
Elliott Investment Management LP’s reported 13F position in each company the letter names, in the quarter ending on or before the letter and the quarter after. Shown because the letter names the company. A letter is commentary; it is not a record of why a position changed.
CDK CDK Global, Inc. · Subject of the letter
The 13F Explorer has no record for CDK, so no position is stated.
Everything Elliott Investment Management LP reports (13F) · Every letter beside its positions