Thomas Gayner · Markel Group
Letter to Business Partners
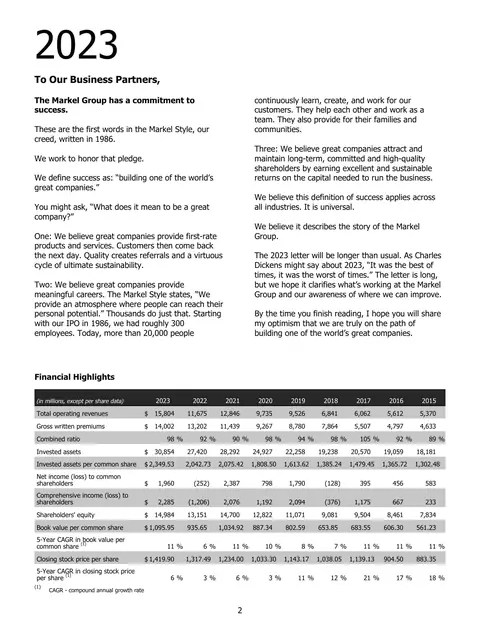
Markel Group's 2023 letter to business partners
Covers FY2023Published 6 Mar 2024Available at SEC.gov, link checked 7 Oct 2026Shareholder letter · Investment
Letter begins on page 5 of 155. A large file (20.4 MB): on mobile data, it may take a while to open.
The view as filed on 6 Mar 2024, not a statement of what the author thinks today.
What to notice
- 1
The Orange and Blue method: Orange is investments and cash less debt, per share; Blue is normalised operating earnings after interest and tax, times a conservative and consistent multiple, per share. Added together they give Markel's sense of intrinsic value.
Continue the investment thesis
See the 3 remaining takeaways on what this investor is arguing and why, and every analysis across the Letters & Theses library.
Checking what you can open…
“We would wither away if we didn’t embrace change.”
Why read it
It explains, in a chief executive's own words, a simple two-part method for estimating intrinsic value per share and how that estimate guides decisions to repurchase or issue shares.
About this letter
Thomas S. Gayner, chief executive officer of Markel Group, wrote this letter to the company's business partners at the front of its 2023 annual report. He warns at the outset that the 2023 letter will be longer than usual, borrowing Dickens to call the year the best of times and the worst of times.
The letter is framed by the Markel Style, the creed the company wrote in 1986, and by its definition of success as building one of the world's great companies. It reports on each of what Markel calls its three engines: insurance, where the company fell short of its goals; Markel Ventures, the majority-owned non-insurance businesses it began acquiring in 2005; and investments. It closes with the four basic choices for allocating the capital the group generates and with how management estimates intrinsic value per share.
Companies
- Markel Group Inc. MKL
Themes
- capital allocation
- valuation
- mistakes
- risk
- long term ownership
- culture
A large file (20.4 MB): on mobile data, it may take a while to open.
L3VLUP does not host this document. It belongs to Markel Group and is a public SEC filing; the notes above are L3VLUP’s reading of it.
More from Markel Group
The same argument, elsewhere
- Berkshire Hathaway's 2011 letter to shareholders · Warren Buffett, Berkshire Hathaway
- Berkshire Hathaway's 2005 letter to shareholders · Warren Buffett, Berkshire Hathaway
- John Elkann's 2025 letter to Exor shareholders, on a difficult year · John Elkann, Exor
- Source Capital's 2025 letter to shareholders, on Microsoft and low credit spreads · Source Capital Portfolio Managers, FPA
The ideas in this letter, on Atlas
Holdings named in this letter
Markel Group Inc’s reported 13F position in each company the letter names, in the quarter ending on or before the letter and the quarter after. Shown because the letter names the company. A letter is commentary; it is not a record of why a position changed.
MKL Markel Group Inc. · The writer’s own company
- Before the letter
- 31 Dec 2023 (Q4 2023 13F): not among Markel Group Inc’s listed positions. A holding below the listed range, under another security, or none at all would read the same.
- After the letter
- 31 Mar 2024 (Q1 2024 13F): not among Markel Group Inc’s listed positions. A holding below the listed range, under another security, or none at all would read the same.
Everything Markel Group Inc reports (13F) · Every letter beside its positions